Posts

Game of roulette: Software development effort estimation - II,How ‘knowing software effort estimation is more about biases and human misjudgment’ can help Part 2: Authority & Availability Bias  

Image
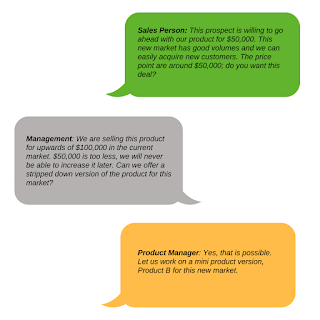
Earlier i n Part 1 I talked about Anchor bias at play in bid management, Agile poker planning and a sales situation. In part II of this series I share my opinion on Authority and Availability bias at play in estimations. Authority bias is the tendency to attribute greater accuracy to the opinion of an authority figure (unrelated to its content) and be more influenced by that opinion. It is a conditioned bias that make us ‘believe’ individuals dressed as  doctors talking about a particular toothpaste brand, people seeming like police, lawyers or government authorities talking about law, Senior or management though non-technical make better technology or project choices !  In order to make short cuts  & make easier choices as humans we implicitly follow authority.      Have you seen the technology choices and solution direction changed because the management wanted Jack to review the solution ?  ‘Mr Jack of all  ‘ lacks ma...
Image
Game of roulette: Software development effort estimation  - Part I - ‘K nowing software effort estimation is more about biases and human misjudgment’ can help us make better decisions  Software effort estimation is by definition ‘mapping the unknown’, an approximation game. There are various techniques to estimations including processes like WBS, analogy based estimation, poker planning, models like expert estimations, group estimations etc. The consensus among industry practitioners is techniques, process and tools when used well and topped with right reviews should create reasonably accurate estimations. This is far from the truth ! The role of human biases and influences on development effort estimations is accepted, but they are not widely discussed or accepted. Effort estimations are actually fertile grounds for human misjudgment.        "Man is not a rational animal, he is a rationalising animal” - Robert A. Heinlein For exa...

Girlfriend experience expectation syndrome : How IT service provider relationships often suffers from biases

[Mental models and its application for better product management decisions] It is very common that companies who outsource product development to external IT service providers expect that they help the company reduce product development uncertainties by being true partners i.e. charter unknowns technology landscape by taking risks alongside, understanding unknown technical choices, trying them out and recommending what would work best in the project. In IT services parlance, this concept is sold to the customers using fancy terms like skin in the game, extended arm of customers, true partners, etc etc.  Most often this arrangement never works, we almost always hear the disappointment from the product managers that a particular service provider is not adding value, they just are not up the curve to be able to provide the right technical choices to be made and at best they execute what is being told to them and thats about it.   Expecting an outsourcing IT service ...

Views: Banking at the bottom of the pyramid: EKO Financial services

When i wrote about the need for banking for a common man in poor Indian villages in February 2009 little did i know that just about the same time elsewhere a start-up was working on this idea. Yesterday this start-up was featured in the Times of India. The company i am talking about is EKO financial services started by Abhishek sinha and Anubhav sinha. This start-up tied up with SBI to offer no frills account to the people representing the bottom of the pyramid. A common man can walk to a store, similar to buying a Sim card on furnishing identity documents can open an account within 10 minutes. And similar to recharging his mobile currency can deposit money into his account by handing over cash to the shop keeper who acts as a customer service point of EKO. Money transfers can be through the phone. I am immensely happy to see this innovation happening at the grass root levels and also very optimistic about the future of this goldmine. All the best to EKO team. The following video shows...

Paper Series: Incrementally rewarding your customers based on profitability

Image
Publications: CFO , Rfpconnect Volume based incremental or tiered pricing is not new to most of the banks. Banks use this technique to incrementally drive revenues from existing customers by giving him volume pricing or discounts. Depending on the capability of the product system, banks may decide to keep the competitive price definition inside or outside the system. The challenge is in building in tremendous flexibility by parametrization of the solution. A white paper co authored by me is published in CFO.COM and RFPCONNECT.COM

Views: Islamic Banking

Image
I wanted to write the first blog of the year about a banking practice that is based on ethics. About 8 years back I had first heard about Islamic banking from Mr. Srinivasan, then the vice president at i-flex. He described Islamic banking as 'Allah gives and Allah takes', an interest free banking practice. For a long time it stayed in my mind as a funny cultural and unsustainable practice that was funded by the crazy oil rich Middle Eastern states. But, since my interactions with banks in Saudi Arabia, UAE and Bahrain, etc I started to better understand the underlying principles of Islamic banking. According to the holy Koran, the Shariah is what is acceptable to Islam. There are a set of Islamic values that are in general applicable to all practices of trade and also applied to the banking practices. Shariah prohibits interest or a time value for money. Money as such is not a marketable commodity, but an instrument that can be only put into productive use based on the values...

Research: Costing in transaction banking services and cost based pricing

Image
One of the casualties of a recessionary environment is the luxury of not changing the way businesses price their products and services. In order to keep up their top lines, most organization have started innovating their pricing strategies moving it closer to the transaction based model, factoring in the risk and cost. Knowing the cost at various levels is relevant for price optimization, capacity utilization and operational efficiency. As there is a growing importance to measure the productivity and profitability of service delivery channels like ATM, Internet payment gateways, branches, etc Banks need to implement costing practices at various departments. Today costing is generally a grey area in banks. This is because most banks do not know what exactly the cost of an individual transaction level is. Unlike manufacturing industries where cost at an individual unit can be arrived easily, banks product cost cannot be fully arrived at until it is consumed, and the costs are distributed...

Views: Believing in what you have done, Patience and just sitting back

Image
I cannot help but think how things go awfully wrong many a times because you as an individual or organization has not believed on what he/it has done through the long time it takes to take the tree to bear fruits.I have seen so many instances both professionally and personally now, how things have gone off track just when you do not know how close you are to where you wanted to go. One of the primary reasons for things to go amuck i see is interference, taking actions for too many things too many times. My travel to Africa couple of weeks back was a challenge on my patience. I got a seat next to a lady with a fussy kid. The kid cried, slept, cried, slept, cried slept.... and the cycle continued till we reached Dubai. I did not know what went through the kid and why it was crying. The kid did not let it self be put on the seat belt and was rolling all over creating a mess. I was loosing patience and had a deep urge to scare the child so much that it kept quite for the rest of the journe...

Opinion: Banks and Google wave: whats in it for a common user ?

Image
I watched the google wave developers demo on friday since i was curious about its potential. It has already created waves on the internet and is currently being talked about as the next big thing coming from google. Google wave is a communication protocol built on the principles and architecture of operational transformation . It is a client and server based solution that google aspires to release as an open source so that organization can implement their own wave servers and clients into which their users could login and communicate. So what is a wave and whats in it for an organization like banks and users like me and you that would make our life simpler and more powerful ? Google wave is a new way of communication that integrates real time messaging, emails and other powerful features into a convergent platform. Waves could be created and sent across multiple users just like email. The waves enable users to concurrently communicate with other users in real time where changes made b...

Views: Does your bank have Customer data pollution ?

Image
Over the last three years, any bank i met up with irrespective of the region, size, how tech savvy the bank is, or if the bank had a data warehouse or an enterprise CRM; all had a common concern 'The challenge is clean customer data' . Essentially, since most banks operate on a silo mode, the customer information gets defined in different places to varying levels of data quality, leading to a 'Polluted customer data' from an enterprise point of view. This is a concern for all banks going in for any new enterprise solution since interfacing and data quality is an issue. The question is 'how do you identify and link up the related customers defined at various business silos'? This answer is in the quality of customer data and the available parameters. In some countries regulations have played their part in the solution by implementing KYC (countries like India now lay a lot of emphasis on KYC) norms. With KYC, linking up customers is possible using parameters like...

Views: Nigerian Banks, F1 and IPL !!

Its been a week of Nigeria, F1 and IPL2 for me. I am almost ready to leave back to Bangalore and it was a week of witnessing the new emerging players, tremendous competition and good performance exhibition under unfavorable circumstances. Firstly the F1 race at Shanghai, it is the first ever win (first and second place) for the Red bull team and Vettel's performance was excellent given the competition and toughest of the wet weather conditions. Red bull has not been the favorites of the teams but now its definitely something to watch out for, way to go!! IPL season 2 going on at South Africa is nothing short of spectacular, especially since what Lalit modi managed to achieve in a short notice of 3 weeks. Between all the internal politics (interesting blog by the fake IPL player !!), pressures among the teams to stay on the league tables and weather challenges I think IPL has managed to be a great success with a decent media coverage everywhere (even in a not so cricket crazy countr...

Opinion: Banks and Revenue Leakages!

What do you and me as individuals do when the going gets tough economically? Double check our telephone bills? See if we used them more than we should have; check if there is a better plan out there with better rates which was not so important before? Weigh whether to use your car or public transport now depending on the need to use. Make sure that you bought groceries and vegetables at the best rates that were never so important since you loved the place you shopped more than the value. Double check all the rebate coupons that you never cared to check on before. There are two keys things that I am talking about, one is controlling the overhead costs or expenditures and the second is plugging the leakages that existed before but you cared less. I believe similar to this, banks in today's environment will have to closely consider performance metrics like costs, profitability of product and revenue leakages. Measurement of costs and product profitability are in practice today, but i...

Views: Banking for the unbanked - contd...

To continue on product innovations, to reach newer segments of the banking market i was thinking about telecom. Why there is such an explosive growth(in terms of reach to common man) in telecom industry versus a hindu rate of growth when it comes to traditional banking. I am not talking about the 20% growth in revenues the banks are making by doling out home loans and credit cards to the consuming public at various interest rates. I am talking about parallel's to pre paid cards, small recharge tickets available at the beedi shops, life time free incoming facilities, bundled products like land line + internet + IPTV, etc that is making telecom companies add 3-4 million subscribers month on month. Is it that the need for a common man to have banking facility is minimal when compared to his need to communicate? I think the answer to this is the way we understand customer segmentation. Unlike the uniformity in need to communicate, the need to have banking services varies widely across ...

Views: Banking for un-banked?

I have been thinking quite a bit lately on what innovation could mean to the mass market at the bottom of the pyramid. A lot has been written about the bottom of the pyramid in recent years, that the next level of growth will come from this market. I think this is evident from the emergence of Indian economy. Take for example my self; I come from that strata of society that had seen so much less banking facilities, all by virtue of the economic levels I came from. Today after ten years I am in a good job and now there is a whole set of banks chasing business from me because I have shifted my economic orbit. I think there is a whole generation of Indians today who are very frequently shifting their economic orbits because of the sustainable growth in the economy. And this, is further fueling the growth that has already set in. But, if you think from the bank's perspective, has this change come because of any innovation from bank’s side to reach to those different levels in the socie...

Paper series: European payments scenario – becoming a level playing field

Introduction The evolution path the Banking industry has witnessed in the last few years with Consolidations, Expansions, Electronic Banking in Retail, Developments in Risk management, the evolution of the Euro single currency and subsequently the innovations in payments has made the European banking scene more active than ever. At different points in time the Banks have faced challenges in achieving the above, powered by organizational growth aspirations in serving the customer base and driven by regulatory changes affecting the banking industry. The most recent regulatory changes are the efforts of creating a level playing field in payment instruments in Europe by creating a faster, transparent, standard and cost effective payment infrastructure. OFT (Office of fair trading) in UK and SEPA in European union. This change in direction offers immense challenges for Banks in terms of scaling its IT capabilities and increased competition in the market... read on

Paper series - Value propositions of a core banking solution vs pricing and billing solution

Publications : finextra ,  bankingcrossing, financial Introduction Banks have started realizing the importance of pricing as a banking enterprise entity. Core banking solution such as Flexcube, Temenos or Finacle fits well as a technology solution for a banks’ day to day business. However a core banking solution itself cannot cater to all the needs for fee based income of a bank. This is attributable to the complex nature of banks operations across its business areas. The banks are often unintentionally grown into a complex structure with its independent departments often referred to as silos having their own systems tied together to a centralized core banking system. Each of these silos has its own product bundles and offerings and a technology component to capture the fee income for the bank. So what comes out over a period of time is a severe disability to visualize the fee income or pricing of such charges at the level of an enterprise. In this article we will discuss, how core ba...